Grants vs Loans for College: What Students Need to Know
Understand the key differences between grants and loans, and learn how to maximize free aid while minimizing debt for college.
By Frederick Hill
Picture this: you have just opened your financial aid award letters, and the numbers are swirling. One school offers a generous package of scholarships and grants. Another leans heavily on federal loan options. The difference in out-of-pocket cost is stark, and the long-term implications are even more significant. For many families, this is the moment when understanding grants vs loans for college what students need to know becomes not just helpful, but essential. Choosing the right mix of funding can mean the difference between graduating with manageable debt and spending decades paying off a loan that seemed small at the time.
This guide breaks down the core differences between grants and loans, explores the most common types of each, and offers a practical strategy for maximizing free money while minimizing debt. By the end, you will have a clear framework for evaluating your own financial aid offers and making a confident decision that supports your academic and financial future. Whether you are a high school senior comparing packages or an adult learner returning to school, the principles here apply to every level of study, from certificates to graduate degrees.
What Are College Grants?
Grants are a form of financial aid that does not need to be repaid. They are typically awarded based on financial need, although some are merit-based. Think of a grant as a gift that is applied directly to your educational expenses, including tuition, fees, books, and sometimes living costs. Because they are not loans, they do not accrue interest, and you are not required to make payments after graduation. This makes grants the most desirable form of aid, and every student should exhaust all grant options before considering borrowing.
The most common source of grant aid is the federal government, but states, colleges, and private organizations also offer grants. For example, the Federal Pell Grant is the cornerstone of need-based aid for undergraduates. For the 2025-2026 award year, the maximum Pell Grant is $7,395, though the exact amount depends on your Expected Family Contribution (EFC), cost of attendance, and enrollment status. Other federal grants include the Federal Supplemental Educational Opportunity Grant (FSEOG) and the Teacher Education Assistance for College and Higher Education (TEACH) Grant. State grants, such as the Cal Grant in California or the TEXAS Grant, often mirror federal need-based criteria. Institutional grants come directly from your college, using its own funds to lower your net price.
Key Features of Grants
- No repayment required: Once awarded, the money is yours to use for qualified education expenses.
- Need-based or merit-based: Most grants are need-based, but some reward academic, athletic, or artistic talent.
- Limited funding: Grants are often capped, and many have application deadlines or require the FAFSA to be filed early.
- Potential for early disbursement: Funds are typically sent directly to your school, and any leftover amount is paid to you.
While grants are fantastic, they rarely cover the full cost of attendance. For instance, a student with a $10,000 tuition bill might receive a $5,000 Pell Grant, leaving a $5,000 gap. That gap is where loans often come into play, which is why understanding the full financial picture is critical.
What Are Student Loans?
Student loans are borrowed money that must be repaid with interest. They are available from the federal government and private lenders, such as banks, credit unions, and online financial institutions. Unlike grants, loans create a legal obligation. You must repay the principal amount plus interest, regardless of whether you complete your degree or find a job in your field. This is the fundamental trade-off: loans enable you to attend college now, but they consume future income.
Federal student loans are generally the first choice for most borrowers because they offer fixed interest rates, income-driven repayment plans, and forgiveness programs for public service workers. Private loans, on the other hand, often have variable rates and fewer borrower protections. For the 2025-2026 academic year, the federal Direct Subsidized Loan interest rate is 6.53% for undergraduates, while the Direct Unsubsidized Loan rate is 7.53%. Graduate students face rates around 8.53% for Direct Unsubsidized Loans and 9.08% for Grad PLUS loans. Private loan rates can range from 4% to 15% or more, depending on your credit score and the lender.
Types of Federal Student Loans
- Direct Subsidized Loans: For undergraduates with demonstrated financial need. The government pays the interest while you are in school at least half-time and during deferment periods.
- Direct Unsubsidized Loans: Available to both undergraduate and graduate students, without a need requirement. You are responsible for all interest from the moment the loan is disbursed.
- Direct PLUS Loans: For graduate students or parents of dependent undergraduates. These carry higher interest rates and require a credit check.
Borrowing is not inherently bad. For many students, a reasonable amount of federal loan debt is a smart investment in a degree that increases earning potential. The danger arises when borrowing exceeds what your expected salary can support. For example, borrowing $30,000 to earn a teaching degree where starting salaries average $45,000 is a different risk profile than borrowing $120,000 for a degree with a $35,000 starting salary. The key is to calculate your projected monthly payment against your expected income, a concept known as the debt-to-income ratio.
Grants vs Loans: A Direct Comparison
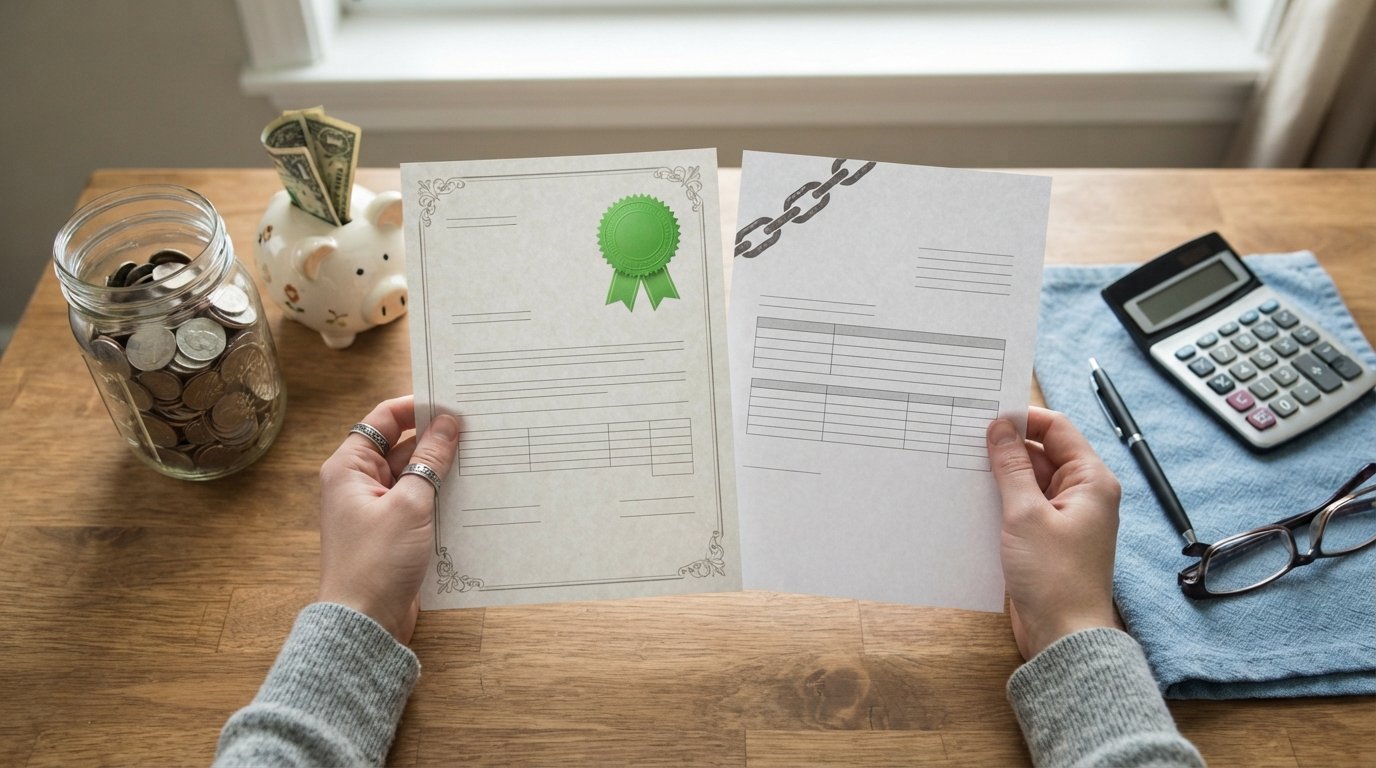
When you line up grants and loans side by side, the differences become clear. The table below summarizes the key contrasts, but the most important takeaway is that grants are free money, while loans are borrowed money with a future cost.
| Criteria | Grants | Loans |
|---|---|---|
| Repayment | Not required | Required, with interest |
| Basis | Financial need or merit | Credit history (private) or no credit check (federal) |
| Interest | None | Accrues over time |
| Maximum amount | Limited by program (e.g., Pell Grant cap) | Can cover full cost of attendance (federal limits apply) |
| Impact on future | No financial burden | Monthly payments, credit score impact |
This comparison is not meant to scare you away from loans, but rather to underscore that loans should be used only after you have secured all available grants, scholarships, and work-study opportunities. The ideal financial aid package is one that maximizes gift aid and minimizes borrowed funds. For example, a student who receives a $7,395 Pell Grant and a $5,000 state grant at a public university with a $12,000 tuition has nearly covered their costs without borrowing. In contrast, a student who receives no grants and borrows $12,000 per year for four years will graduate with nearly $50,000 in debt, even before interest capitalization.
Real-world scenarios illustrate this best. Consider Maria, a first-generation college student. She files the FAFSA and receives a Pell Grant, an institutional grant, and a work-study award. Her remaining gap is $3,000, which she covers with a small federal loan. After graduation, her monthly payment is manageable because her debt is low. Now consider James, who does not file the FAFSA and relies on private loans to cover his entire tuition. He graduates with $80,000 in debt at a 10% interest rate, leading to a monthly payment near $1,000. That payment consumes a large portion of his entry-level salary, delaying other life goals. The difference is not about intelligence; it is about having a strategy.
How to Maximize Grants and Minimize Loans
The process of securing grants starts long before you enroll. It begins with filing the Free Application for Federal Student Aid (FAFSA) as early as possible after October 1 each year. The FAFSA is the gateway to all federal grants, most state grants, and many institutional grants. Missing the priority deadline can mean losing out on limited funds, so mark your calendar. The FAFSA also determines your eligibility for subsidized loans, which are cheaper than unsubsidized ones due to the interest subsidy.
Beyond the FAFSA, research scholarships from private foundations, community organizations, and employers. Many students overlook local scholarships because they have smaller awards, but they add up. For instance, a $500 scholarship from a local Rotary club might seem minor, but it is $500 you will not have to borrow. Additionally, some colleges require the CSS Profile for institutional aid, which is a separate application. Check with each school's financial aid office to understand its specific requirements.
When you receive your financial aid award letter, compare the grants and loans side by side. Look at the net price, which is the cost of attendance minus all grants and scholarships. This is the true amount you need to cover through savings, income, or loans. If the net price is higher than you can afford, you have options: negotiate with the financial aid office, appeal for more aid if your family's circumstances have changed, or consider a more affordable school. Remember, a more expensive school with a generous grant might actually cost less than a cheaper school with no aid.
If you do need to borrow, start with federal student loans. They offer fixed rates, flexible repayment plans, and potential forgiveness. Private loans should be a last resort, and only after you have exhausted federal loan limits. When comparing private lenders, look at the interest rate, origination fees, and repayment terms. A lower interest rate can save thousands over the life of the loan, but also consider the borrower protections that private lenders may lack, such as deferment for economic hardship.
Special Considerations for Online and Career-Focused Students
For students pursuing online degrees or career-focused certificates, the same principles apply, but there are a few nuances. Online programs often have lower tuition than their on-campus counterparts, which can reduce your overall borrowing need. However, you still need to complete the FAFSA to access federal grants and loans. Many online students are adult learners who are balancing work and family, and they may be eligible for grants such as the Pell Grant if they have not yet earned a bachelor's degree. Additionally, some employers offer tuition assistance, which is essentially a grant from your job, so check with your human resources department.
Career-focused programs, such as those in trades, healthcare, or technology, may have shorter durations and higher earning potential, making loans more viable. For example, a two-year nursing associate degree might cost $20,000 in total, but new graduate nurses often start at $70,000. In that case, borrowing $20,000 is a reasonable investment. Conversely, a certificate in an oversaturated field with low starting salaries might not justify any borrowing. Before enrolling, research the program's graduation rate, job placement rate, and median salaries for graduates. This data is often available on the school's website or through the U.S. Department of Education's College Scorecard.
As you explore your options, you may find it helpful to use a college matching service to compare programs. For example, a platform like CheapOnlineEducation can help you browse sponsored online and campus degree programs by subject and state. You can request information from multiple schools, compare their offerings, and evaluate costs without any obligation to apply or enroll. This can be a valuable tool for building a shortlist of affordable programs that align with your financial and academic goals.
Building a Financial Aid Strategy
Ultimately, understanding grants vs loans for college what students need to know is about empowerment. You are not a passive recipient of financial aid. You are an active decision-maker who can shape your financial future. Start by completing the FAFSA early and accurately. Then, research all available grant opportunities, from federal to local. When you receive award letters, compare the net prices, not just the total aid amounts. If loans are necessary, borrow conservatively and understand the terms. Aim to keep your total student debt below your expected first-year salary, a rule of thumb that many financial experts recommend.
Another critical step is to revisit your financial aid package each year. Your circumstances may change, such as a parent losing a job or a sibling enrolling in college, which could increase your grant eligibility. You can also appeal your award if a school gives you less than you need. Write a polite letter to the financial aid office explaining your situation, and provide documentation. Many schools are willing to adjust their offers, especially if you have received a better package from a competing institution.
For those who are still in high school, take advantage of Advanced Placement (AP) or dual-enrollment courses to earn college credit for free. This reduces the number of semesters you need to pay for, which lowers your total cost. Additionally, consider starting at a community college, where tuition is significantly lower, and then transferring to a four-year institution. This path can cut your total tuition bill by thousands of dollars, effectively reducing your need for loans.
One often overlooked aspect is the importance of maintaining Satisfactory Academic Progress (SAP). To remain eligible for grants and loans, you must meet your school's SAP standards, which typically require passing a minimum number of credits and maintaining a certain GPA. If you fall behind, you could lose your aid, forcing you to take out private loans or drop out. Stay organized, attend classes, and seek academic support early if you are struggling.
Finally, do not ignore the psychological weight of debt. The stress of loan repayment can affect your career choices, such as avoiding lower-paying but more fulfilling jobs, and can delay major life milestones like buying a home or starting a family. By choosing a financial aid package that prioritizes grants and minimizes loans, you are investing in your future well-being, not just your education.
In the end, the choice between grants and loans is not a simple one, but it is a manageable one. By understanding the mechanics, comparing your options, and making deliberate choices, you can graduate with the degree you want and a debt load you can handle. As you move forward, keep this comparison in mind: every dollar you receive in grants is a dollar you will not have to earn later, and every dollar you avoid borrowing is a dollar you will not have to repay with interest. That perspective will guide you toward a brighter financial future.